Best Credit Cards in Switzerland 2026: Free Cards & Cashback
If you live in Switzerland and want a credit card, four things matter: annual fee, cashback, foreign currency fee and cash withdrawal fees. That’s what this comparison looks at. For most Swiss residents in 2026, the best single credit card is the Cembra Certo! One Mastercard: no annual fee, 1% cashback at three shops you choose yourself, and Mastercard acceptance. If you want more cashback, pair the Amex of poinz or the Swisscard Cashback Cards (1% on almost all purchases) with the Certo as a Mastercard backup. For travel and foreign-currency spending, no Swiss credit card is the right tool. Use a debit card such as Neon, Revolut, or Yuh and keep a real credit card only for hotel and rental-car deposits.
Our Picks by Use Case
| Use Case | Recommended Card | Why |
|---|---|---|
| Best single credit card | Cembra Certo! One | No annual fee, 1% cashback at 3 shops of your choice, Mastercard |
| Maximum cashback | poinz Amex or Swisscard Cashback Amex + Certo | 1% on the Amex, Certo as backup where Amex isn’t accepted |
| Travel and foreign currency | Neon / Revolut / Yuh + Cumulus as credit backup | Swiss credit cards are expensive abroad; Cumulus has no explicit FX fee but a rate markup |
| Premium / frequent traveller | Cornèrcard Platinum | Only if you actually use lounge access, travel insurance, and the concierge |
Overview: the best credit cards
| Card | Annual Fee | Cashback / Points | Foreign Currency Fee |
|---|---|---|---|
| Cembra Certo! One Card | CHF 0 | 1% at 3 Shops, otherwise 0.25% | 1.5% |
| poinz Credit Cards * | CHF 0 | 1% (Amex), 0.25% (Visa) | 2.5% |
| Swisscard Cashback Cards | CHF 0 | 1% (Amex), 0.25% (MC/Visa) | 2.5% |
| Migros Cumulus Credit Card | CHF 0 | 1% (Migros), 0.33% (otherwise) | No separate fee, Migros Bank rate |
| Coop Supercard Credit Card | CHF 0 | 1 point/CHF (Coop), 1/3 otherwise | No separate fee (1.5% on CHF abroad) |
| Cornèrcard Platinum | CHF 500 (CHF 250 in 1st year) | 0.9% (CHF), 1.7% (foreign currency) | max. 1.2% |
Five of the six cards in this comparison have no annual fee. The premium Cornèrcard Platinum justifies its higher fee with lounge access and travel benefits, covered further down. All of them work regardless of where you bank. You pay the bill by direct debit or eBill, for example. An eBill is only paid automatically if you set up a standing approval. Switching costs you almost nothing in convenience.
Best Credit Cards by Use Case
Best for everyday use: Cembra Certo! One
If you want one free Swiss credit card and don’t want to think about it again, the Certo is the cleanest pick. No annual fee, 1% cashback at three shops you pick from a list (including Migros, Coop, SBB and Digitec), and 0.25% on other purchases (excluding cash withdrawals and TWINT payments, for example). It’s a Mastercard, so acceptance is rarely a problem.
Don’t use it abroad. The 1.5% foreign currency fee and 3.75% cash withdrawal fee (minimum CHF 10) eat the cashback within a single trip.
Best for maximum cashback: poinz or Swisscard Cashback Amex plus Certo
Among the free cards in this comparison, only an American Express pays 1% on almost all purchases. Exclusions include cash withdrawals, fees and gambling. Both poinz and Swisscard Cashback offer that rate on their Amex. The catch is acceptance: American Express is accepted at over 150,000 points in Switzerland, including Migros, Coop and SBB, but you still get turned down at smaller retailers, pharmacies, parking machines, and some restaurants.
The second card in the duo (Visa at poinz, Mastercard or Visa at Swisscard) only pays 0.25%, the same as the Certo’s base rate. So the better setup is poinz or Swisscard Amex for everything that accepts Amex, plus the Certo as a Mastercard backup for the rest. If you go this route, poinz has the better mechanics: you can redeem the cashback after each paid monthly bill, while Swisscard credits it only once a year.
Best for travel and foreign currency: don’t use a Swiss credit card
There is no Swiss credit card that beats a good debit card abroad. In this comparison, the Certo charges a 1.5% foreign currency fee and the poinz and Swisscard Cashback cards charge 2.5%. Cumulus and Coop Supercard charge no separate fee, so the cost sits in the exchange rate. For the Cumulus, Moneyland measured an average markup of 3.13% over the reference rate on euro payments.
For card payments and cash withdrawals abroad, use a debit card from Neon, Revolut, Yuh, or Wise. We compare them in our guide on the best Swiss cards without foreign transaction fees. I don’t recommend Radicant: BLKB announced that the bank will be wound down in an orderly liquidation.
Keep one Swiss credit card with you for the situations where a debit card won’t work: hotel deposits, rental cars (especially in the US), and other pre-authorisations. Among the cards here, the Cumulus is a reasonable choice for this because no separate foreign currency fee is added on top of the rate markup.
Best premium card: Cornèrcard Platinum, only if you use the benefits
The Cornèrcard Platinum (CHF 500/year, CHF 250 in the first year) bundles unlimited Priority Pass lounge access, travel insurance, and a concierge service. The American Express Platinum (CHF 900/year) is another premium option on the Swiss market. It adds a CHF 100 SWISS voucher per year, CHF 200 a year in SIXT ride credit (eight rides at CHF 25, registration required), and CHF 40 per quarter in dining credit when you pay at least CHF 250 in one go at a participating restaurant (offer runs until 31 December 2026). But you pay close to twice as much.
These cards only make sense if you actually use the benefits. A standalone Priority Pass Prestige membership with unlimited member visits costs USD 469 a year for US residents, and guests pay USD 35 per visit. If you’re in a lounge a few times a year, use the included travel insurance instead of buying a separate policy, and spend the dining or travel credits, the math works. If those benefits sit unused, you’re handing the issuer several hundred francs.
For Miles & More fans: SWISS Miles & More Cards
Only worth it if you’re already in the Miles & More ecosystem and want to top up your balance. As long as you make at least one mile-earning purchase a month and have held the card for at least a month, your miles don’t expire. Annual fees for the card duo are CHF 120 (Classic), CHF 220 (Gold), and CHF 700 (Platinum), with a 2.5% foreign currency fee across the range. As a pure cashback card it’s a poor choice. If you fly SWISS regularly, you can exchange miles into Points and Qualifying Points once a year, and then the Gold or Platinum can pay for itself.
Card-by-Card Details
Cembra Certo! One Card
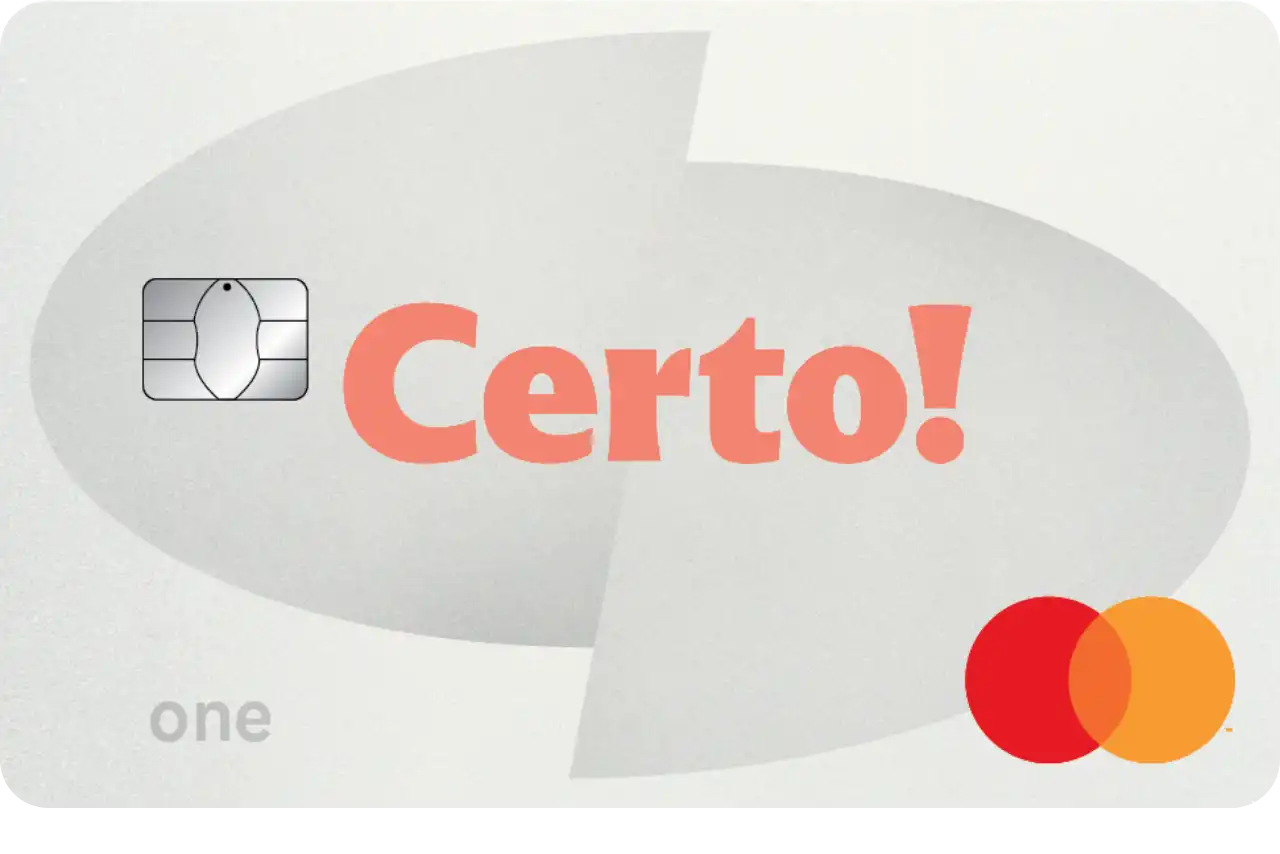
CHF 0
1% at 3 Shops, otherwise 0.25%
1.5%
3.75%, min. CHF 10
Special Features
No annual fee, including supplementary cards
Shops chosen from a list (e.g., Migros, Coop, SBB, Digitec)
Modern app and mobile payment (Apple Pay, Google Pay, Samsung Pay)
Best price guarantee up to CHF 3,000 per year
SOS Assistance up to CHF 100,000 per person
The Cembra Certo competes mainly with the Migros Cumulus credit card, and for most people it wins.
- No annual fee, including up to five supplementary cards in the same household
- 1% cashback at three shops of your choice from a list. Including Migros, Coop, SBB, and Digitec
- 0.25% cashback everywhere else
The bonus program is attractive because you pick the three shops yourself according to your spending. Cashback is credited automatically to the card statement once a quarter.
The app is modern and supports Apple Pay, Google Pay and Samsung Pay. The card also includes a useful insurance package:
- Best-price guarantee up to CHF 3,000 per year and CHF 2,000 per event
- Purchase insurance up to CHF 2,000
- Travel insurance with SOS Assistance (up to CHF 100,000 per person and event)
- 24/7 emergency call centre
- Medical transport and repatriation
- Search and rescue costs
The insurance only applies if you paid at least 51% of the item or trip with the card. The weak spot is foreign use. Purchases abroad carry a 1.5% fee, and cash withdrawals are 3.75% with a CHF 10 minimum.
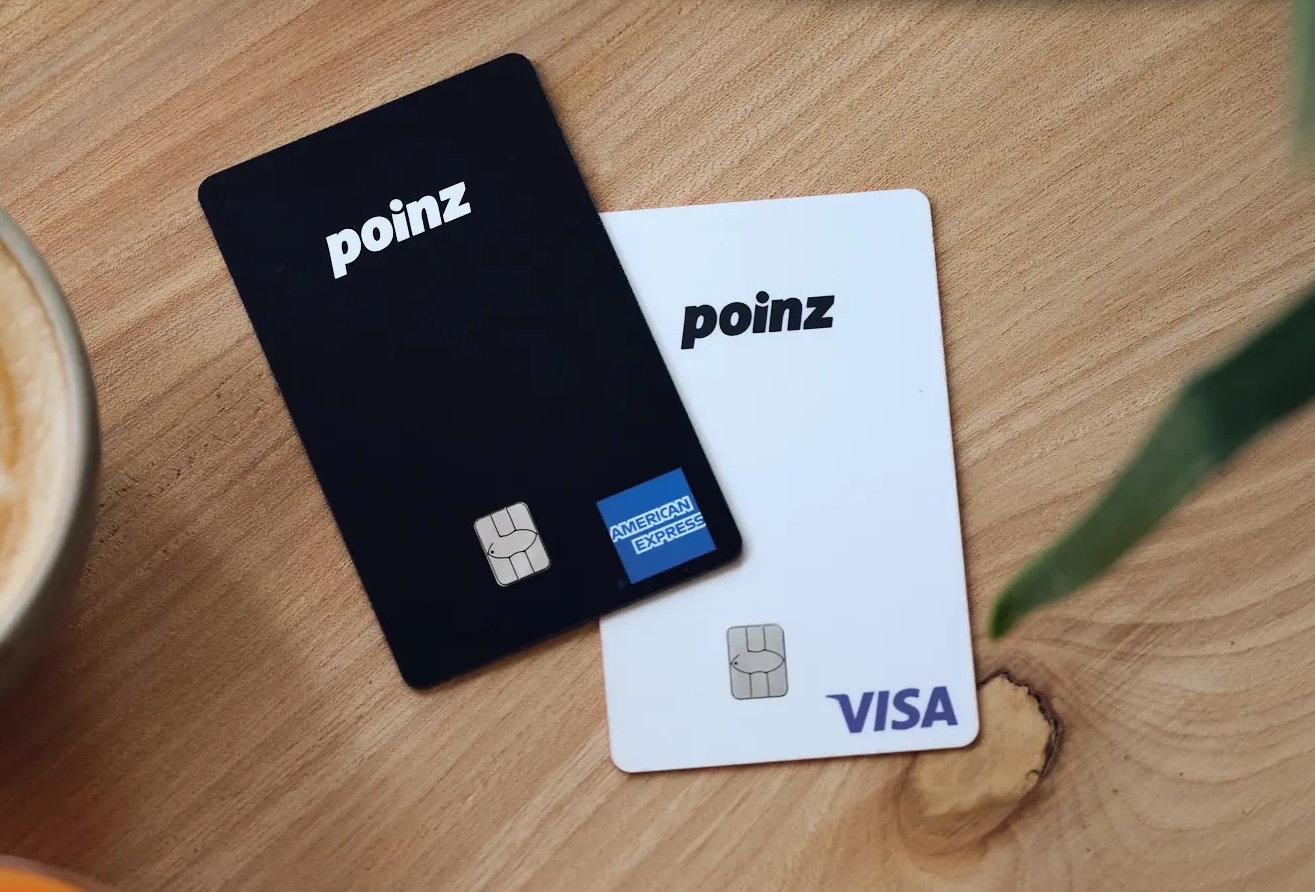
poinz Credit Cards
CHF 0
1% (Amex), 0.25% (Visa)
2.5%
4%, min. CHF 10
Special Features
No annual fee, including supplementary card
Cashback in the poinz account within 24 hours (provisional)
3% welcome cashback on the Amex for the first 3 months (max. CHF 100)
Extra cashback in the poinz Shop, depending on merchant and offer
Goods return insurance up to CHF 1,000
Currently a CHF 100 Coop voucher as a welcome gift
The poinz credit cards are a white-label product of the Swisscard Cashback Cards. Both are issued by Swisscard AECS GmbH. poinz is a duo of American Express and Visa; the Cashback Cards pair the Amex with a Mastercard or Visa. The cashback rates are the same: 1% with the Amex, 0.25% with the second card. The foreign currency fee, cash withdrawal fee and goods return insurance match too. The main difference is when you get your cashback.
Redeemable monthly instead of once a year
With the Swisscard Cashback Cards, you see the cashback you earn on your monthly statement, but it’s only credited once a year. If you cancel before then, the current year’s cashback is forfeited. With poinz, the cashback shows up in your poinz account within 24 hours as a provisional balance. You can redeem it once the monthly Swisscard bill has been paid. From a balance of CHF 100 you can pay it out to your bank account (5–7 business days), or use it in the poinz Shop for digital vouchers.
The poinz Shop as an extra
You can use the poinz Shop without the cards too, but it fits well with them. In the poinz Shop you earn extra cashback at partners such as Apple, Decathlon, Kärcher, or Solis. Rates depend on the merchant and current offers; poinz advertises up to 30%. Digital vouchers, for example for H&M, Spotify, or Zalando, also yield extra cashback. If you actively use the shop, your effective cashback rate can rise above the 1% from card purchases alone.
Current welcome offer
If you apply for the poinz credit cards via our partner link* you receive a CHF 100 Coop voucher on top of the 3% welcome cashback in the first three months.
Conditions at a glance
- No annual fee, including supplementary card
- 1% cashback with the Amex, 0.25% with the Visa, also abroad
- 3% cashback in the first 3 months with the Amex (max. CHF 100)
- Cashback shows up in your poinz account within 24 hours as a provisional balance
- Foreign currency fee 2.5% plus exchange rate markup of 1 to 2%
- Cash withdrawal 4%, minimum CHF 10
- Goods return insurance up to CHF 1,000 per purchase (from CHF 60 goods value, unused and fully functional goods, return refused within 90 days, at least 50% paid by card)
In daily use you have two accounts: poinz (app or website) for your cashback, and the Swisscard app for the bill and balance.
The same rule on foreign use applies as for the Cashback Cards. A 2.5% foreign currency fee is more than the cashback, and it also applies to payments abroad charged in Swiss francs. Keep the poinz cards for Swiss merchants.
My take: if the Cashback Cards appeal to you, the poinz cards are the better choice in practically every respect. Same card, same issuer, faster access to your cashback, more flexible use of it. The only extra effort is running two accounts in parallel.
Swisscard Cashback Cards
CHF 0
1% (Amex), 0.25% (MC/Visa)
2.5%
4%, min. CHF 10
Special Features
No annual fee, including supplementary card
Maximum cashback (1% Amex, 0.25% MC/Visa)
Card duo: Amex + Mastercard or Visa
Goods return insurance up to CHF 1,000
5% welcome cashback on the Amex for new customers (3 months, max. CHF 100)
Very good customer service
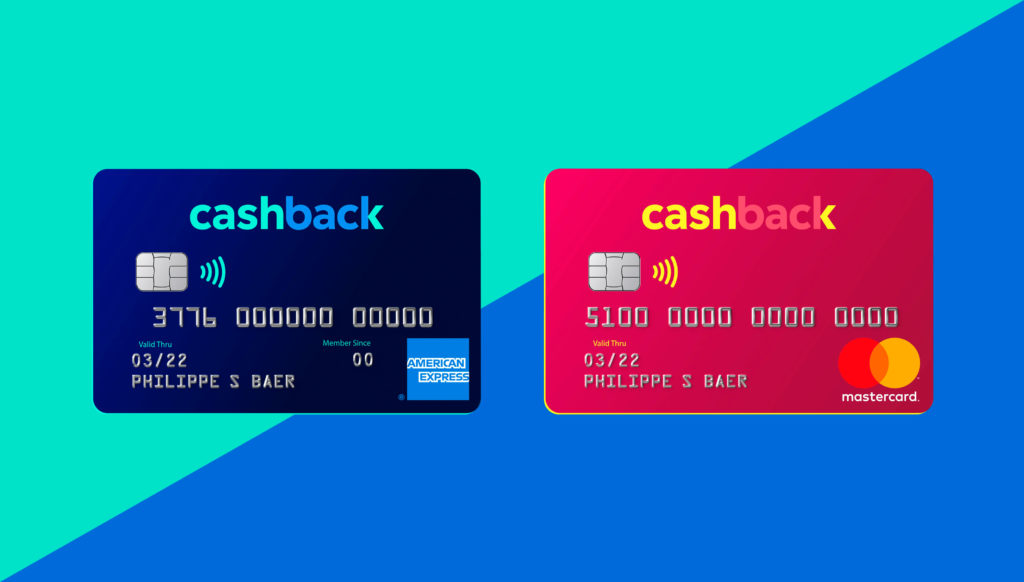
The Cashback Cards are offered as a duo: an American Express and either a Mastercard or Visa.
- No annual fee, including supplementary card
- 1% cashback on American Express
- 0.25% cashback on Mastercard and Visa
- 5% welcome cashback on the Amex in the first three months (up to CHF 100), new customers only
- Foreign currency fee: 2.5%
- Cash withdrawal in Switzerland and abroad: 4%, minimum CHF 10
A useful extra is the goods return insurance:
- Worldwide coverage up to CHF 1,000 per purchase
- Applies to unused, fully functional goods from CHF 60, at least 50% paid by card
- Applies when the seller refuses to take the item back within 90 days
For pure cashback maximisation in Switzerland, this is the right product. Amex acceptance is high enough that you can use it most of the time, including at Migros, Coop and SBB. Still, carry the Mastercard or Visa as a backup.
Don’t use these cards abroad. The foreign currency fee is 2.5%, and cash withdrawals are 4% with a CHF 10 minimum. Swisscard is, on the other hand, known for very good customer service.
Migros Cumulus Credit Card
CHF 0
1% (Migros), 0.33% (otherwise)
No separate fee (Migros Bank rate)
Free (Migros) / abroad 2x p.a. free up to CHF 500, then 2.5%, min. CHF 10
Special Features
No annual fee, including supplementary card
No separate foreign currency fee
Collect Cumulus points
Free cash withdrawals at Migros
Search and rescue costs up to CHF 60,000
Online protection and travel insurance
The long-popular Cumulus credit card is issued directly by Migros Bank. Compared to the Certo, the main advantage is the conditions abroad.
- No annual fee, including up to three supplementary cards
- No separate foreign currency fee
- Free cash withdrawals at Migros tills (up to CHF 1,000 per withdrawal and day)
- Two free cash withdrawals per year abroad (up to CHF 500 per withdrawal), then 2.5%, minimum CHF 10
- 1 Cumulus point per CHF 1 spent at Migros
- 1 Cumulus point per CHF 3 spent outside Migros
It also comes with a comprehensive insurance package:
- Search and rescue costs up to CHF 60,000
- Trip interruption insurance up to CHF 4,000
- Best price guarantee up to CHF 2,000
- Purchase and transport insurance up to CHF 2,000
- Online account protection up to CHF 10,000
- Online legal protection up to CHF 10,000
- 24/7 emergency assistance
Trip interruption, the best-price guarantee and purchase insurance require at least 60% of the cost paid by card.
You collect Cumulus points directly: 500 points equal a CHF 5 voucher at Migros. So you get 1% on Migros spending and about 0.33% elsewhere. You do get the Migros points anyway if you just scan your Cumulus card and pay with another card. That’s why the Certo beats it on raw cashback unless you want the Cumulus ecosystem. But the Cumulus has one job the Certo can’t do as well: a credit card with no separate foreign currency fee for hotel deposits and car rentals abroad.
“No foreign currency fee” needs a footnote. There’s no extra fee, but Migros Bank sets the exchange rate. Moneyland measured an average of 3.13% above the reference rate on euro payments. For day-to-day spending abroad, debit cards like Neon, Revolut, or Wise remain cheaper. Which credit card costs least abroad is covered in our guide to cards without foreign transaction fees.
Coop Supercard Credit Card

CHF 0
1 point/CHF (Coop), 1/3 otherwise
No separate fee (1.5% on CHF abroad)
3.75%, min. CHF 5/10 (CH/Abroad)
Special Features
No annual fee, including supplementary card
Collect Superpoints (1 point/CHF Coop, 1/3 outside)
Superpoints convertible to miles
Free travel and flight accident insurance
15% discount on Europcar rentals
Coop’s counterpart to the Migros Cumulus credit card. The conditions:
- No annual fee, also for the supplementary card
- 1 Superpoint per CHF 1 at Coop (with the Supercard, even without the credit card)
- 1 Superpoint per CHF 3 spent outside Coop
- No separate foreign currency fee, but 1.5% on payments abroad in Swiss francs
- Cash withdrawals 3.75% (min. CHF 5 in Switzerland, CHF 10 abroad)
It also includes basic travel and flight accident insurance, plus travel advice and assistance.
Superpoints are versatile: you can pay with them at Coop at a rate of 100 points per CHF 1, or convert them to miles in the Miles & More frequent flyer program of Swiss. Apart from that, there isn’t much to say. The issuer is TopCard Service AG, and the app is outdated compared to the competition. There’s no separate foreign currency fee, so the cost sits in the exchange rate.
Worth it if you absolutely want to collect Superpoints. If not, put Coop into your three Certo shops and pick up flexible 1% cashback instead.
Cornèrcard Platinum
CHF 500 (CHF 250 in 1st year)
0.9% (CHF), 1.7% (foreign currency)
max. 1.2%
4%, min. CHF 10 (ATM)
Special Features
Unlimited Priority Pass lounge access
Concierge service
Comprehensive travel insurance
Cashback of 0.9% in CHF and 1.7% in foreign currency
The Cornèrcard Platinum is the main premium card on the Swiss market. The headline points:
- Annual fee CHF 500 (CHF 250 in the first year)
- Unlimited Priority Pass lounge access for cardholder and one guest
- Concierge service through the Sincura Group
- Cashback: 0.9% on purchases in Swiss francs, 1.7% on purchases in foreign currency
- Hertz discount: at least 15% in Switzerland, up to 10% abroad
- Access to the Cornèrcard Emotions benefit world
- Mobile payment (Apple, Google, Samsung Pay)
- Up to 3 free Gold supplementary cards
The insurance package is the strongest of any card here:
- Trip cancellation up to CHF 60,000
- Medical emergencies up to CHF 1.5 million
- Baggage insurance up to CHF 15,000
- Warranty extension by 2 years on electronics (up to CHF 6,000)
- Purchase protection up to CHF 15,000 per year, CHF 5,000 per event
The travel insurance requires at least 51% of the travel costs paid by card. Cashback of 0.9% in Swiss francs and 1.7% in foreign currency partly offsets the fee. You redeem it from CHF 25, and it’s credited to the card. For international use, Cornèrcard charges a moderate foreign currency fee of up to 1.2%. Cash withdrawals cost 4% at ATMs (min. CHF 10) and 4% at bank counters (min. CHF 15); abroad, the foreign currency fee can come on top. Heavy cash users are better off elsewhere.
The Cornèrcard Platinum pays for itself for frequent travellers who use lounges and the concierge. For everyone else, the free options above are cheaper and almost as good.
Why “Best” Depends on Where You Spend
A Swiss credit card behaves like a different product depending on what you do with it.
In Swiss francs at Swiss merchants, cashback actually matters. A 1% card on CHF 20,000 of yearly spending pays back CHF 200. There are no foreign currency fees in the way, and the only question is which loyalty program or partner you’d rather earn into.
The moment you pay in a foreign currency, the picture flips. Depending on the card, you pay a foreign currency fee of up to 2.5% or a markup in the exchange rate, and some cards also charge a fee on Swiss franc payments abroad. That typically wipes out the entire year’s cashback in a single trip. That’s why no Swiss credit card belongs at the top of a “best for travel” list. Use a separate debit card for that.
Acceptance is the second split. American Express works in big retailers, hotels, restaurants, and most online shops. It still gets refused at smaller retailers, parking machines, pharmacies, and some restaurants. That’s why a 1% Amex setup needs a Mastercard or Visa backup. Since the second card in the poinz and Swisscard duos pays the same 0.25% as the Certo’s base rate, the Certo is a more useful backup than the second card in the same duo.
The third split is the one most people forget: true credit card versus debit card. Hotels and rental car companies place a hold on your card for the deposit. With a debit card, that money is blocked in your account; with a credit card, it only uses part of your credit line. In the US, rental companies often accept debit cards only under conditions, Enterprise for example for certain airport rentals with a return ticket. That alone is a reason to keep one free Swiss credit card around even if you use a debit card every day.
Mastercard Is Not the Same as Mastercard: Debit vs. Credit
For a long time, Swiss debit cards (the old “EC cards”) were issued as Maestro or V-Pay cards. They worked in shops and at ATMs but rarely online, and acceptance abroad was patchy.
Today, debit cards are issued as Mastercard or Visa. They usually work online and abroad too, although not every merchant accepts debit cards. At first glance they look identical to credit cards. The difference is in what happens when you pay. A debit card is linked directly to your bank account. Pay CHF 17 for a burger and your available balance drops by CHF 17 right away, though the booking often posts a few days later. If the account is empty, the payment is usually declined.
A credit card gives you a line of credit, usually a few thousand francs. The CHF 17 burger doesn’t come out of your bank account. You owe the issuer CHF 17, and your available limit drops from CHF 3,000 to CHF 2,983. Once a month, you get a bill for everything you’ve charged since the last one.
Use credit cards responsibly. Spend only what you have. Otherwise you build a balance with the issuer at high interest. Since 1 January 2026, the legal maximum interest rate for credit cards is 12% a year, and 10% for cash loans. Several issuers charge the full 12%; the Cumulus charges 10.4%. That’s by far the most expensive credit any Swiss bank will sell you.
Why You Want at Least One Credit Card
Even if you can pay online and abroad with your debit card today, there are reasons to keep a credit card.
Bonus programs
Almost every credit card has a bonus program. The reward is usually between 0.25% and 1% of what you spend. Not life-changing, but on CHF 20,000 a year that’s CHF 50 to CHF 200 back.
Security
Credit card transactions aren’t debited from your bank account immediately. If your card falls into the wrong hands, you must have it blocked right away and dispute wrong charges in writing in time, within 30 days of the statement date at Swisscard. Until then, the money in your bank account isn’t directly affected.
Car rentals and hotel deposits
Deposits abroad are easier with a credit card. A CHF 1,000 deposit on a rental car blocks credit-line space, not real money in your account. Especially in the US, some rental companies don’t accept a debit card for the deposit in every case. A credit card removes that friction.
Frequently Asked Questions
What is the best credit card in Switzerland in 2026?
For most Swiss residents it’s the Cembra Certo! One Mastercard. No annual fee, 1% cashback at three shops you choose, and Mastercard acceptance. It’s not the right card for heavy foreign-currency use.
Which Swiss credit card has the best cashback?
Among the free cards in this comparison, the American Express in the poinz or Swisscard Cashback duo pays 1% on almost all purchases. poinz pairs the Amex with a Visa, Swisscard with a Mastercard or Visa, each at 0.25%. The Certo pays 1% only at three chosen shops. With poinz you can redeem the cashback after each paid monthly bill; Swisscard credits it once a year.
Is the Cembra Certo better than the Migros Cumulus?
For most people, yes. With the Certo you choose three shops at 1%, including Migros if you want. The Cumulus only pays 0.33% outside Migros. The Cumulus does have one real advantage: no explicit foreign currency fee, which makes it the better fallback when a hotel or rental car abroad needs a credit card deposit.
Is the Migros Cumulus card really free abroad?
Sort of. There’s no separate foreign currency fee, but Migros Bank sets the exchange rate. Moneyland measured an average of 3.13% above the reference rate on euro payments. You still pay, just inside the exchange rate instead of on a separate line. For cheaper payments abroad, see our guide on cards without foreign transaction fees.
Is American Express accepted in Switzerland?
Mostly. Big retailers, hotels, restaurants, and most online shops take Amex. Smaller shops, parking machines, pharmacies, some bakeries, and some restaurants don’t. Carry a Mastercard or Visa as a backup.
Should I use a Swiss credit card abroad?
For everyday card payments and ATM withdrawals, no. Use a debit card from Neon, Revolut, Yuh, or Wise. Keep a Swiss credit card with you only for hotel and rental-car deposits.
Do I need a credit card for hotels and rental cars?
It often makes things easier. Hotels and rental companies place the deposit as a hold on your card. With a credit card, that only uses your credit line, not your bank balance. Some rental companies, especially in the US, accept debit cards only under conditions. A free Swiss credit card such as the Certo or Cumulus is enough if the rental company accepts it, the available credit covers the rental plus the deposit, and the card is in the driver’s name.
Can foreigners and new residents in Switzerland get a Swiss credit card?
Usually yes. Depending on the card, issuers ask for ID or a residence permit and details of your income. Which permits they accept varies by issuer. For the credit check, they also request information from ZEK. Until the card arrives, a debit card from Neon, Revolut, or Yuh covers everyday spending.
Conclusion
The Swiss credit card market in 2026 clearly shows that the best offers don’t come from traditional banks but from specialised financial service providers and retailers. A few practical takeaways follow from that.
Free cards dominate the basic segment. With the exception of the premium card, none of the products compared here charge an annual fee. The expensive bank-card packages have nothing to offer that a free card can’t match.
Cashback Cards vs. poinz: same issuer, different experience. If you’re after maximum cashback, the Swisscard Cashback Cards and the poinz credit cards are technically identical. Both are issued by Swisscard with the same conditions. The concrete advantages of poinz: you can redeem the cashback every month instead of once a year, and there’s a CHF 100 Coop voucher as a welcome gift. The poinz Shop adds extra cashback at partners, but you can use it without the cards too.
Insurance is hidden value with strings attached. The included insurance packages can replace expensive separate policies in an emergency. Some covers only apply if you paid a minimum share with that card, for example 51% for the Certo and Cornèrcard’s travel insurance, or 60% for some Cumulus cover. Conditions vary by benefit. Plenty of cardholders don’t know what their card covers and forget to claim. When the card arrives, read the insurance overview once and treat it as a bonus, not a substitute for proper travel or cancellation insurance.
Premium only if you’ll use the benefits. The Cornèrcard Platinum costs CHF 500 a year. For frequent travellers who actually use the lounge, insurance, concierge, and cashback, the math works out positive. For anyone else, a free card plus a separate Priority Pass would be cheaper.
The bigger picture: a credit card is a strategic financial instrument. Sticking with the card in your main bank’s package and paying a few hundred francs a year is no longer the path of least resistance. Look at how you actually spend, then pick the right card or two. Most Swiss residents will be best served by the Certo plus one of poinz or Swisscard Cashback, with a debit card on top for foreign currency.
*Affiliate link: If you sign up for the poinz credit cards via this link, we receive a commission from the provider. There are no additional costs for you.