Charles Schwab International Review 2026 for Swiss Investors
The US broker Charles Schwab offers a brokerage option for Swiss customers with their Charles Schwab International Account. We opened one ourselves as Swiss residents, and the debit card was delivered to Switzerland without any issues. In this article, we will look at the key features and fees of Charles Schwab and compare them with Interactive Brokers.
About Charles Schwab
The figures come from Schwab’s account page and pricing guide.
| Account maintenance fee | free |
| Inactivity fee | free |
| Currency exchange fee | up to 3% |
| Trading US stocks and ETFs | free (online) |
| Trading non-US stocks | USD 50 per trade |
| Minimum deposit | none |
| Debit card | Free Visa debit card with worldwide fee reimbursement |
| Deposit currencies | CHF possible (automatically converted to USD) |
Why a US Broker?
Many Swiss investors want to invest in ETFs domiciled in the USA. However, many European brokers like Degiro only offer a limited selection of US ETFs. Instead of the popular Vanguard VTI ETF, one must limit themselves to European ETFs like the Ireland-domiciled Vanguard VWRL, which has higher fees compared to its American counterpart. Additionally, for Swiss investors, US ETFs are more advantageous from a tax perspective, as the 15% US withholding tax on dividends can be credited in Switzerland with form DA-1.
Charles Schwab vs Interactive Brokers
So we know that to access the best ETFs, we need a US broker. There are two major players in Switzerland for this: Charles Schwab and Interactive Brokers. Let’s look at both based on a few criteria:
- Fees: Schwab charges no trading fees for US trades.
- Minimum deposit: Neither requires a minimum deposit.
- Currency exchange: Deposits at Schwab are automatically converted to USD, with a markup of up to 3%. At Interactive Brokers, you can deposit CHF and exchange it for USD at competitive rates.
- User-friendliness: Both have a functional user interface. While both are somewhat technical and not entirely easy to use, Interactive Brokers is considered by us to be slightly more modern and easier to navigate.
- Debit card: Schwab offers a Visa debit card that refunds any fees for cash withdrawals abroad. Interactive Brokers does not offer anything like this.
Overall, Interactive Brokers offers a better package, especially because of the ability to deposit Swiss francs directly. Otherwise, the two brokers are not significantly different. However, Schwab is an excellent option for those who want a second broker or need a debit card for travel.
Currency Exchange
The biggest disadvantage of Charles Schwab is that while you can deposit Swiss francs, they are automatically converted into USD. According to the pricing guide, Schwab charges a markup of up to 3% for this. The same markup applies if you withdraw money in Swiss francs.
If you do not earn your money directly in dollars, it is best to use a third party for currency exchange. Interactive Brokers offers by far the best conditions for this. You would transfer your Swiss francs to Interactive Brokers, exchange them there at ideal rates for USD, and then wire the funds to your Schwab account. However, it should be noted that Interactive Brokers does not look favorably on customers solely using their brokerage account for currency exchange.
Another option is Wise. This service is specifically designed for currency exchange. However, the fees here are higher than at Interactive Brokers.
| Interactive Brokers | 0.002%, minimum USD 2 |
| Wise | around 0.3% and higher |
| Charles Schwab | up to 3% |
Minimum Deposit
According to the account page, Charles Schwab has no minimum deposit for individual or joint accounts. You also don’t need to maintain a minimum balance.
This makes Schwab worthwhile for smaller amounts too, or if you mainly open the account for the debit card.
Debit Card
Charles Schwab has another advantage that no other bank or broker in Switzerland can offer: a debit card that allows you to withdraw cash worldwide for free. And “free withdrawal” does not only mean that Schwab does not charge fees. It also means that fees charged directly by the ATM are immediately refunded by Charles Schwab.
The card is a Visa debit card linked to the Schwab One brokerage account. According to the account agreement, it is issued by BNY Mellon Investment Servicing Trust Company. Don’t confuse it with the Schwab Bank Visa Platinum card, which is only available to US residents.
Here’s a practical example:
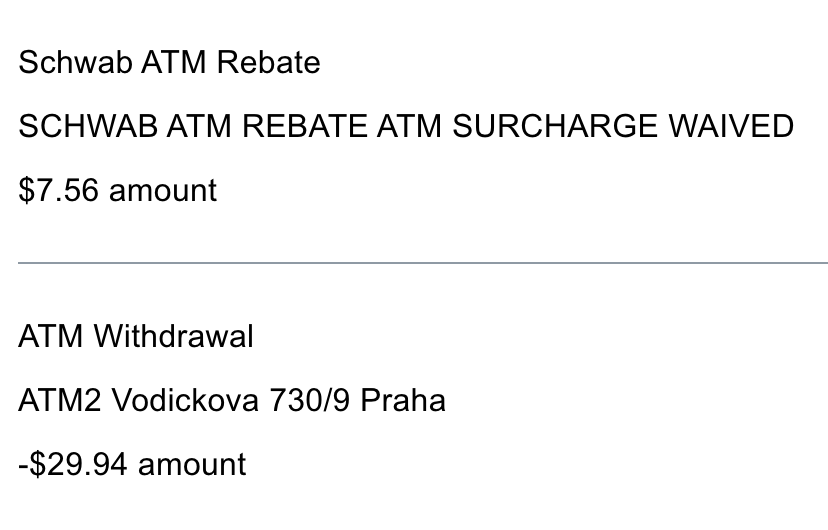
- Withdrawing 500 Czech Crowns (CZK) at an ATM in Prague
- The ATM charges a fee of 170 CZK
- The total cost of the transaction is around USD 30
- Schwab immediately refunds the USD 7.56 fee
Simply put: There is no better way to withdraw cash than with the Schwab debit card, especially in countries where ATMs impose an additional fee. For frequent travelers, having a Schwab account can be beneficial solely because of the debit card, even without investing in securities.
Conclusion
Charles Schwab International has two decisive advantages: trading US securities without fees and a debit card that allows free cash withdrawals worldwide. And with no minimum deposit, the account is open to smaller investors too.
The major disadvantage is currency exchange, with a markup of up to 3% when depositing Swiss francs directly. However, you can use cheaper services like Wise or Interactive Brokers. Thus, you can first exchange Swiss francs at Interactive Brokers and then send them directly in USD to Schwab.
In our opinion, Interactive Brokers remains the best broker for Swiss investors. There is no minimum deposit, you can exchange Swiss francs affordably, and the interface is modern and user-friendly. You’ll find more options in our broker comparison.
So who would benefit from a Schwab account? On one hand, it’s great for travelers wanting to withdraw cash worldwide. Frequent travelers can quickly save over CHF 100 a year in ATM fees, particularly when traveling often outside of Europe, where ATMs frequently charge additional fees.
Charles Schwab is also an ideal second broker to Interactive Brokers. If someone does not want to invest all their money with IBKR, they can allocate part of it at Schwab and still benefit from US ETFs. However, it is recommended to do the currency exchange at IBKR.